 0 minutes
A bank statement for a Canada visitor visa is more than a document showing how much money you have.
For Indian applicants, the bank statement can help explain your overall financial situation: your regular income, savings, spending pattern and whether you have enough money for the proposed visit.
That is why a large or recent deposit can sometimes create questions.
For example, imagine your account normally contains ₹3–4 lakh, but a few weeks before your Canada visitor visa application, ₹10 lakh is credited to the account.
The issue is not simply that the balance is high.
The more important question is:
Where did the ₹10 lakh come from, and can you demonstrate that the money is genuine and available to you?
IRCC’s current visitor-visa guidance says that bank-account statements can help officers understand whether an applicant has enough money to support themselves during their stay. The guidance asks for at least six months of account details, including balances, to help IRCC understand the applicant’s financial situation.
However, there is no universal Canada visitor visa rule saying that a particular large deposit automatically causes refusal, and there is no universal minimum bank balance applicable to every visitor.
The right approach is therefore not to hide or artificially manipulate a transaction.
Instead:
Identify the deposit → explain the genuine source → connect it to your financial circumstances → provide appropriate evidence.
This guide explains how Indian applicants can do that properly.
IRCC does not assess your bank balance in isolation.
For a Canada visitor visa, you must satisfy an immigration officer that you have enough money for your stay and that you will leave Canada at the end of your visit. IRCC also considers ties such as a job, home, financial assets or family.
Your financial documents should therefore make sense alongside the rest of your application.
A bank statement can help demonstrate:
IRCC’s current visitor-visa guidance specifically lists a bank account statement as a recommended document and says the statement should identify the bank, demonstrate that the account belongs to you and provide at least six months of account details, including balances.
This is why applicants should avoid looking at only the closing balance.
For example:
₹12 lakh balance + unexplained ₹8 lakh recent credit
can require more context than:
₹12 lakh balance built through regular salary and savings over time.
The final balance alone does not tell the complete financial story.
Not automatically.
A large deposit can be completely legitimate.
People receive significant amounts of money for many genuine reasons, including:
The important issue is whether the transaction can be understood and supported if clarification is required.
A large deposit becomes more difficult when:
The practical principle is simple:
A large deposit is not automatically suspicious. An unexplained large deposit can create questions.
No universal fixed bank balance applies to every Canada visitor visa applicant.
IRCC states that the amount of money needed depends on factors including how long you will stay and whether you will stay in a hotel or with friends or relatives.
This is important because many online articles publish statements such as:
“You need ₹10 lakh for a Canada visitor visa.”
or:
“You need ₹15 lakh in your account.”
Such claims should be treated cautiously unless they are specifically based on the circumstances of a particular applicant.
There is no one bank-balance number that guarantees approval.
A two-week tourist trip and a longer family visit can have very different financial requirements.
Similarly, an applicant staying with relatives may have different accommodation costs from someone paying for hotels throughout the trip.
Your finances should therefore be considered in relation to your actual proposed trip.
Consider this example.
An applicant’s six-month account history looks like this:
| Period | Approximate balance |
|---|---|
| Month 1 | ₹2.8 lakh |
| Month 2 | ₹3.1 lakh |
| Month 3 | ₹3.4 lakh |
| Month 4 | ₹3.2 lakh |
| Month 5 | ₹3.7 lakh |
| Month 6 | ₹3.5 lakh |
| One week before application | ₹11.5 lakh |
The final balance may look financially comfortable.
But the account history also shows that approximately ₹8 lakh arrived shortly before the application.
That does not mean the applicant should be refused.
It means the applicant should be able to explain the transaction if it is relevant to the financial picture being presented.
For example:
“The ₹8,00,000 credit represents the maturity proceeds of my fixed deposit.”
That statement becomes much more credible when supported by evidence showing:
Fixed deposit → maturity → proceeds → bank credit
The same principle applies to other legitimate transactions.
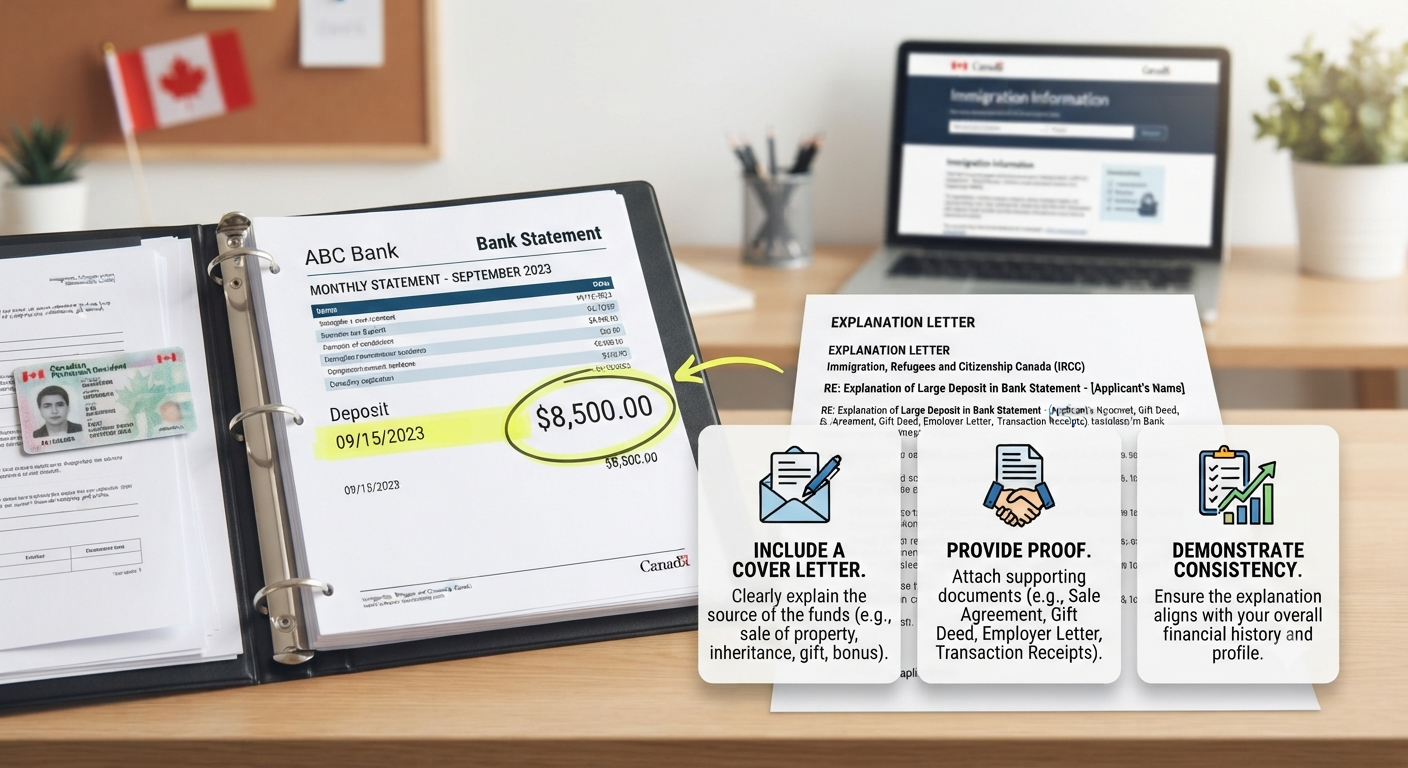
If you have a significant deposit in your bank statement, use a simple four-part approach.
Start with the exact transaction.
Mention:
For example:
“A credit of ₹7,50,000 was received in my savings account on 15 August 2026.”
Avoid vague statements such as:
“I recently received some money.”
Specific information makes the explanation easier to understand.
Next, explain exactly where the money came from.
For example:
The explanation should describe what actually happened.
Do not select a source simply because it sounds more acceptable.
If the funds are being used to finance your Canadian trip, explain that clearly.
For example:
“These funds are part of my personal savings and are available for my proposed travel expenses.”
If the money is not being used for the trip, do not incorrectly present it as travel money.
The application should accurately reflect who is paying for the visit.
Where appropriate, connect the deposit to documentary evidence.
The objective is to create a traceable financial chain.
For example:
Investment statement → redemption → bank credit
or:
Own Account A → transfer → Own Account B
or:
Property sale → payment → bank credit
The stronger the documentary connection, the easier it is to understand the transaction.
Fixed deposits are common among Indian applicants.
Suppose you have maintained a fixed deposit for several years and it matures shortly before you apply for a Canada visitor visa.
The maturity proceeds are transferred into your savings account, creating a large credit.
This is a legitimate financial event.
Depending on your circumstances:
Your documents should establish the relationship between the investment and the bank credit.
“The credit of ₹6,00,000 on 10 August 2026 represents the maturity proceeds of my fixed deposit held with the bank. I have included the relevant FD documentation and the corresponding bank transaction.”
Keep the explanation factual.
Selling property can result in a substantial one-time deposit.
For example:
Property sold → buyer’s payment → ₹15 lakh credited to account
If the funds are part of your financial resources, explain the transaction rather than presenting the money as accumulated salary savings.
Possible evidence may include:
The exact documents depend on the transaction.
You may sell a car, commercial vehicle or another legitimate asset.
If the resulting payment appears in your bank statement, the source can be explained.
For example:
“The ₹4,50,000 credit represents proceeds from the sale of my vehicle.”
Supporting evidence could include the sale documentation and the corresponding bank transaction, where available.
An applicant may redeem:
The money may then move into a savings account.
A useful documentary trail is:
Investment → redemption → bank account
An investment statement or redemption confirmation can help establish the source.
Employees sometimes receive large amounts because of:
If the transaction is genuine, your salary documentation should make sense with it.
For example, if your employer pays an annual bonus, relevant evidence could include:
Do not describe a bonus as ordinary monthly salary.
Business owners and self-employed applicants can naturally have larger or irregular transactions.
For example, ₹8 lakh may represent payment from a client or proceeds from a business transaction.
Depending on the circumstances, supporting evidence could include:
The important thing is consistency between your declared business activity and your financial records.
This is one of the most common situations.
Suppose you have:
Savings Account A: ₹7 lakh
and:
Savings Account B: ₹3 lakh
You transfer ₹6 lakh from Account A into Account B because Account B is the account you are using for your travel finances.
Account B will now show a large recent deposit.
That does not mean you received new income.
It was simply a transfer between your own accounts.
The best approach is to make the transaction traceable.
Account A
↓ ₹6 lakh transfer
Account B
If appropriate, include evidence from both accounts showing that the money belonged to you.
Do not move money between accounts solely to make your Canada visitor visa bank statement appear stronger.
This is different from transferring your own savings.
Suppose your father, mother, spouse or another family member is genuinely paying for part of your Canadian holiday.
The application should accurately identify the person funding the trip.
Depending on the circumstances, relevant evidence may include:
IRCC’s visitor-visa guidance recognises that documentation can vary according to the circumstances of the application, and applicants should follow the personalised checklist generated in the application portal.
The important point is:
Do not present someone else’s money as your salary or personal savings.
If another person is genuinely paying, say so.
Cash deposits require particular care because the bank statement may show the credit but not necessarily explain where the cash originated.
For example:
₹7 lakh cash deposited into a savings account shortly before the visa application.
The key question becomes:
What is the legitimate source of the cash?
If the money comes from a genuine business transaction, asset sale or another legitimate source, the applicant should be able to provide appropriate evidence.
If you cannot reasonably document the source, do not invent a story.
A visa application is not the place to create an explanation after the fact.
There is no general Canada visitor-visa rule saying that a legitimate deposit must remain in your account for a specific number of days before you apply.
So don’t rely on advice such as:
“Keep the money for 30 days.”
or:
“Wait exactly 90 days after depositing the money.”
The important issue is the genuine source and financial context.
If a legitimate transaction occurred yesterday, waiting three months does not magically change its origin.
Instead, document what actually happened.
At the same time, applicants should avoid making unnecessary last-minute financial movements simply to create a stronger-looking balance.
No—not simply because it is large.
Trying to make your bank statement “look normal” by moving money out can create a more confusing financial picture.
If the money genuinely belongs to you and is available to fund the trip, keep your financial records authentic.
The better strategy is:
Explain genuine unusual transactions rather than manipulate the statement.
Never edit, alter or hide bank records.
IRCC’s current visitor-visa application guidance says that at least six months of account details, including balances, helps IRCC understand your financial situation.
This is different from saying:
“Everyone must submit exactly six months and nothing else.”
Applicants should follow the personalised document checklist generated by IRCC for their application and any applicable instructions for their situation.
The six-month account history is useful because it allows an officer to see more than one isolated balance.
It can show:
That broader context is exactly why a large deposit should be considered alongside the surrounding account history.
No.
This is one of the most important points for Indian applicants.
Canada’s visitor-visa eligibility requirements include demonstrating that you have enough money for your stay, but also that you have ties that will take you back to your home country and that you will leave Canada at the end of your visit.
Therefore:
High balance ≠ guaranteed approval
and:
Lower balance ≠ automatic refusal
The financial evidence needs to make sense in relation to:
Bluebird Next already has a separate article focused on demonstrating return ties for a Canada visitor visa. Because that topic is covered there, this article intentionally focuses on the narrower issue of large deposits and financial-document explanation.
A recently opened account can make the financial history less straightforward because there is less historical activity available to demonstrate how the funds accumulated.
That does not automatically mean the account cannot be used.
But if a new account contains a substantial amount of money, the source and ownership of those funds should be particularly clear.
For example:
Old account → transfer to new account
is different from:
New account → sudden large cash deposit
The supporting evidence should reflect the actual situation.
Do not open a new account solely to create a better-looking bank statement.
Consider these two examples.
An applicant earns ₹1.5 lakh per month.
The bank statement shows:
The financial story is relatively easy to understand.
The applicant earns ₹70,000 per month.
The account normally holds ₹1.5–2 lakh.
Ten days before the visa application, ₹12 lakh is deposited.
The final balance may be high, but the financial story requires additional context.
If the ₹12 lakh comes from a property sale and the applicant can document that transaction, the situation is very different from a deposit for which the applicant cannot provide a credible source.
If you need to explain a significant transaction, keep the explanation concise.
You don’t need five pages describing one bank entry.
A useful structure is:
Date: 15 August 2026
Amount: ₹8,00,000
Source: Fixed-deposit maturity
Reason: Personal investment matured on the stated date.
Evidence: FD maturity document and corresponding bank credit.
If relevant:
The funds are available as part of my personal savings and may be used toward the proposed trip.
The explanation should match your actual documents.
Here is a simple example—not a template to use if the facts are different.
Subject: Explanation of Recent Bank Deposit
I would like to clarify the credit of ₹6,50,000 appearing in my savings account on 12 August 2026.
The amount represents the maturity proceeds of a fixed deposit that I had maintained with my bank. The fixed deposit matured on 12 August 2026, and the proceeds were credited to my savings account.
I have included the relevant fixed-deposit documentation and the corresponding bank transaction to establish the source of these funds.
These funds form part of my genuine personal savings and are available to me for my financial needs, including the proposed expenses associated with my visit to Canada.
I have provided this explanation to ensure that the recent transaction is clear and consistent with my financial records.
The exact wording should change according to your actual circumstances.
If your deposit came from a property sale, do not use an FD explanation.
If it came from your own account, do not call it income.
If a family member funded the trip, identify the sponsor honestly.
If a significant transaction is central to your financial position, don’t assume the final balance tells the whole story.
Do not temporarily borrow money just to show a higher balance and then present it as accumulated personal savings.
Never create a fake property agreement, salary document, investment statement or other evidence.
IRCC states that false or altered documents and false information can lead to serious consequences, including refusal and a ban from Canada of at least five years in cases of fraud/misrepresentation.
If your cover letter says the money came from a property sale but your supporting documents indicate something else, the inconsistency can create unnecessary questions.
Repeated transfers between accounts can make the financial picture more complicated rather than stronger.
The bank statement is useful partly because it shows financial history.
Don’t ignore the transaction pattern.
Before submitting your application, review your financial evidence.
| Check | What to look for |
|---|---|
| Account ownership | Your name and account details are clear |
| Account history | Relevant account history is available |
| Income | Income shown is consistent with your application |
| Savings | Savings pattern is understandable |
| Large deposits | Significant transactions have genuine explanations |
| Transfers | Transfers between your own accounts can be traced |
| Sponsorship | Third-party funding is disclosed accurately |
| Trip cost | Proposed expenses are realistic for your circumstances |
| Employment | Income/employment evidence supports the financial picture |
| Documents | Supporting evidence is genuine and consistent |
IRCC’s current guidance also states that applicants receive a personalised document checklist when applying online. That checklist should be followed along with any additional instructions applicable to the applicant’s situation.
The biggest misconception is that a Canada visitor visa is simply a competition to show the highest bank balance.
It isn’t.
A stronger approach is to build a credible financial story.
For example:
Salary/business income → regular savings → legitimate financial transaction → available funds → realistic Canada trip
If a large deposit breaks that pattern, explain the reason.
If the money came from an investment, show the investment trail.
If it came from a property sale, document the sale.
If it came from another personal account, show the transfer trail.
If someone else is funding the trip, identify that person and provide appropriate supporting evidence.
And if the source cannot genuinely be documented, do not manufacture an explanation.
Not automatically. A large deposit can have a legitimate source. The important issue is whether the financial history and source of funds are genuine and understandable. If the transaction is relevant to the funds being relied upon, supporting documentation can help explain it.
There is no universal fixed bank-balance requirement for every visitor. IRCC says the amount needed depends on factors including the length of the stay and whether you stay in a hotel or with friends or relatives.
IRCC’s current visitor-visa guidance says at least six months of account details, including balances, helps it understand your financial situation. Applicants should also follow their personalised IRCC document checklist.
If the deposit is significant to your financial picture, it is sensible to be prepared to explain its genuine source and provide relevant evidence. There is no universal rule that a particular rupee amount automatically requires a special explanation.
If the money genuinely belongs to you, a transfer between your own accounts can be legitimate. However, you should maintain a clear documentary trail showing the source and ownership of the funds rather than moving money around simply to create an artificial balance.
Yes, applicants may have their trip funded by another person depending on their circumstances. The funding arrangement should be disclosed accurately and supported with appropriate evidence. Do not present a family member’s money as your own salary or savings.
No. IRCC also requires applicants to convince an officer that they have ties to their home country, will leave Canada at the end of the visit and have enough money for their stay.
Submitting false or altered information can have serious immigration consequences. IRCC states that fraud or misrepresentation can result in refusal and a ban from Canada for at least five years.
When preparing a bank statement for a Canada visitor visa, don’t focus only on the final balance.
Focus on whether the financial story makes sense.
A large recent deposit is not automatically a reason for refusal. What matters is whether you can honestly explain:
Where did the money come from?
Why was it received?
Does the transaction match your financial circumstances?
Can you support the explanation with genuine documents?
For Indian applicants, this is especially important because bank statements are not viewed in isolation. Your financial evidence sits alongside your travel purpose, itinerary, employment or business circumstances, family situation and other information in the application.
There is also no magic bank balance that guarantees a Canada visitor visa.
The best approach is transparency and consistency—not artificial deposits, borrowed funds or manipulated statements.
If you have a legitimate large transaction, explain it rather than hide it.
If you are unsure whether your bank statement, income pattern, recent deposit or funding arrangement is presented correctly, reviewing the financial story before submitting the application can help you identify inconsistencies early.
Government of Canada / IRCC — How to Apply for a Visitor Visa: Current guidance on bank statements, six months of account details, travel history, itinerary and employer information.
Government of Canada / IRCC — Visitor Visa Eligibility: Current requirements concerning sufficient funds, ties to the home country and intention to leave Canada.
Government of Canada — Immigration Fraud and Misrepresentation: Official information on false or altered documents and the consequences of misrepresentation.
IRCC Help Centre — False Information: Official guidance confirming that applicants must provide truthful information and documents.
Preparing a Canada visitor visa application is not just about collecting documents. Your application should present a clear and consistent picture of your travel purpose, finances and personal circumstances.
If you have a recent large deposit, unusual transaction, business income, property-sale proceeds, investment withdrawal or third-party funding, Bluebird Next can help you understand how to organise the relevant evidence and explain genuine circumstances clearly.
For Canada visitor visa guidance, document preparation and visa-filing support, explore Bluebird Next and speak with the team before submitting your application.
No consultant can guarantee a visa decision. The final decision rests with the Canadian immigration authorities.
September 18, 2026
September 16, 2026
September 14, 2026

September 11, 2026